Argentine wine brands ranking 2026: the 50 most exported, and number four belongs to Costco
Catena and Alamos lead the January-September 2026 ranking. Kirkland Signature, Costco's own brand, is fourth. Among the top ten, only it and El Enemigo exported more than in 2025. Export value, destinations and price per litre, with a chapter on Europe.
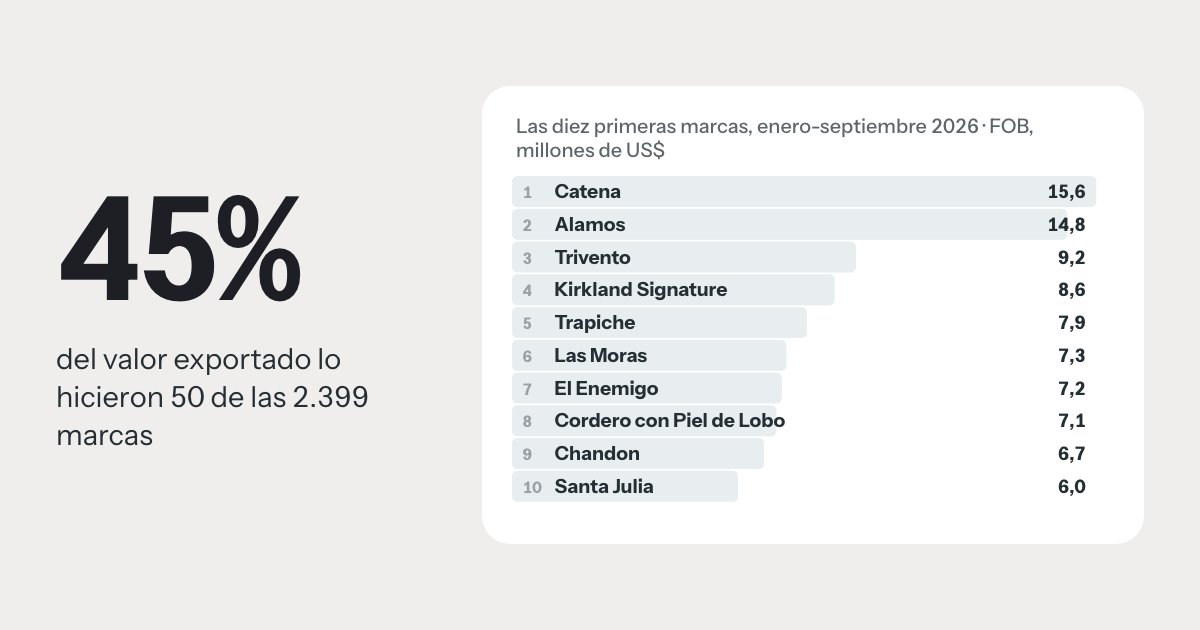
Catena and Alamos, two Catena Zapata brands, lead the ranking of Argentine wine brands for January-September 2026, with US$15.6M and 14.8M. Number four is Kirkland Signature, the own brand of the US retailer Costco.
The brand ranking does not repeat the winery ranking. The top 50 brands totalled US$225.0M, 45% of the series total, while the top 50 wineries account for 71%. Large houses spread their export value across several labels, some of those labels belong to retail chains, and the name under which a wine is declared can change from one year to the next. Each of these moves says something about how a winery exports.
The customs series processed by Vinalitica recorded US$495.4M in wine exports between January and September 2026, 3.5% less than a year earlier. Of that total, US$461.4M was declared with a brand, spread across 2,399 brands; the remaining US$34.0M was shipped with no brand, almost all of it bulk. Within the top 50, 20 brands increased their export value and 30 reduced it. Among the top ten, only two grew: El Enemigo (+11.9%) and Kirkland Signature (+2.3%).
The ranking and how to read it
Brands are ranked by FOB export value, in dollars, as declared in each shipment. Vinalitica merges the different spellings of the same brand using its register, but does not group the brands of the same house: “Trivento”, “Trivento Golden Reserve” and “Trivento Private Reserve” are three rows. The winery shown is the one to which Vinalitica attributes the brand; it may differ from the exporting company and, for retailer own labels, from the owner of the brand.
The 2025 rank and the change compare January-September of both years; when a brand was not declared under that name in 2025, the table shows since when it has appeared. The destinations column counts distinct declared countries; the weight of the main destination is measured on each brand's export value. The average FOB price is that value divided by the litres exported.
Catena Zapata places seven brands in the top 50
Catena (US$15.6M) and Alamos (14.8M) are the two most exported brands, and both belong to Catena Zapata. The winery has five more in the top 50: Catena Zapata, Catena App, Angélica Zapata, DV Catena and Catena Alta. The seven total US$48.2M of the 51.7M the winery exported with a brand, spread across 17 declared brands.
The top two fell: Catena by 22.7% and Alamos by 15.7%. Catena's decline coincides with the appearance of a new name: Catena App has appeared in customs since November 2025 and totals US$3.5M in 2026. Taken together, Catena and Catena App exported 5.2% less than Catena alone a year earlier.
Trivento spreads its export value across four brands in the top 50 (Trivento, Trivento Golden Reserve, Trivento Private Reserve and Trivento Reserve) and Trapiche across three, including Kirkland Signature. That is why the brand ranking is less concentrated than the winery ranking: the top ten brands account for 18% of the series total; the top ten wineries, 35%.
Three retailer brands in the top 50 total US$15.1M
Kirkland Signature, Costco's own brand, is the fourth most exported brand: US$8.6M (+2.3%), attributed to Trapiche according to Vinalitica's brand register. It was shipped to nine destinations, with the United States taking 88% of the value, followed by Mexico, Canada, the United Kingdom and South Korea.
A retailer brand depends on the purchases of a single chain, and its shipments vary widely from year to year. Over January-September, Kirkland Signature recorded US$13.9M in 2022, 6.8M in 2023, 20.2M in 2024, 8.4M in 2025 and 8.6M in 2026.
The other two go to the United Kingdom. Finest Argentina, Tesco's Finest range, which the chain presents as made by the Catena family, grew 54.3% to US$3.7M, with 98% going to that country. Coop, declared by La Riojana with the United Kingdom as its only destination, corresponds to the Fairtrade own-label wines of the Co-op chain, which the cooperative has supplied since 2008: US$2.8M, down 10.3%. Others appear further down the ranking, such as Specially Selected, from Aldi (161st, US$0.5M).
When the declared name changes, the ranking changes
The name under which a wine is declared in customs can change from one year to the next, and that change is information too. Until August 2025, Trivento declared the wines of its Trivento Private Reserve range under the “Trivento” brand; since September it has declared them under that name, with the same product codes. In January-September 2026 the brand totals US$5.7M, 89% of it to the United Kingdom, and moves from 710th to 13th place. Over the same period, the “Trivento” brand fell 28.7% overall and 64.4% in the United Kingdom.
It is not a new wine on the British market: Trivento Private Reserve is the winery's own range, sold in the country's main supermarket chains since at least 2021. What changed is the declared name. Across all its brands, Trivento exported US$9.5M to the United Kingdom, 45.8% more than in January-September 2025.
The pattern repeats at other houses. The appearance of Catena App coincides with Catena's decline, and Trapiche Vineyards, under its own name since March 2023, grew 68.5% while Trapiche fell 23.0%; taken together, Trapiche and Trapiche Vineyards fell 6.1%. A brand's rank should therefore be read alongside the other brands of the same winery.
Eighteen brands send more than half of their value to a single destination
Eighteen of the 50 brands concentrated more than half of their export value in a single declared destination country. For four of them, that country is Brazil: Cordero con Piel de Lobo, eighth with US$7.1M, sends 92% there; Chac Chac, from Las Perdices, 98%; Benjamín, from Nieto Senetiner, 82%; and Trivento Reserve, 100%.
Others depend on the United States (Kirkland Signature, Ed Edmundo, Unánime), Canada (Trapiche, Don David, La Mascota) or the United Kingdom (Finest Argentina, Coop, Trivento Private Reserve). At the other end, Catena, Alamos and Catena Zapata each reached more than 55 destinations.
Europe: half of the value goes to the United Kingdom
Europe received US$145.9M of Argentine wine between January and September (−2.1%), 29% of the series total. The United Kingdom accounts for half: US$72.9M, 3.9% more than in 2025, while the European Union fell 6.9% to 63.1M.
Almost a third of what goes to the United Kingdom carries no brand: US$23.3M, all of it bulk. Among brands, the British ranking is led by Trivento Private Reserve (US$5.0M), Finest Argentina (3.7M), Trivento Golden Reserve (2.9M) and Coop (2.8M): two Trivento ranges and two retailer own brands.
In the European Union, the declared country is not always where the wine is drunk
In the European Union, the leading brand is Salentein (US$2.4M), which declares the Netherlands for 92% of that value. Next comes Cheval des Andes, which declares France for 100% of its shipments to the Union and is sold through the Bordeaux négociants. Chandon and Terrazas de los Andes, of the Moët Hennessy group, also declare France for everything they send to the European Union.
Latvia is the seventh European destination, with US$4.9M, ahead of Ireland, Belgium and Sweden; Luigi Bosca, Las Moras and La Linda are the brands with the most value declared to that country. A destination country can be a distribution platform: the ranking records where the wine was declared, not where it is drunk.
Prices range from US$2 to US$60 per litre
Among the 50, the average FOB price ranges from US$2.16 per litre (San Telmo) to 59.59 (Cheval des Andes), with a median of US$5.33. Catena Zapata, the brand that bears the winery's name, averages US$47.54 per litre and reaches 57 destinations. Among the top ten, El Enemigo has the highest price, US$10.77 per litre.
A brand groups wines that are closer to each other than a winery does, but not a single wine: the average for Catena or Trapiche mixes ranges at different prices. To measure a price segment, you have to classify the shipments, not the brands.
Behind the 50, a long tail of 2,349 brands
The top 50 cut-off is US$1.94M (1.89M in 2025). Only two brands exceeded US$10M in nine months and 14 were between 5M and 10M. At the other end, 1,853 brands, three out of four, exported less than US$100,000 each: together, 9% of the value with a brand.
Entering the ranking: two names first declared in the second half of 2025, Trivento Private Reserve and Catena App, plus Chac Chac (from 56th place) and Navarro Correas Colección Privada (from 51st). Leaving it: Don Miguel Gascón, Los Cardos, Uvita and Piattelli.
What to look at in the brand ranking
A brand's rank says little without the other brands of its winery. Trivento shows it: the brand bearing its name fell 28.7% and kept third place, while the winery, across all its brands, grew 17.1% according to the winery ranking.
In Vinalitica, each brand's profile shows its destinations, the winery to which it is attributed and its month-by-month trend; each winery's profile brings all its brands together.
Method. Source: wine export declarations from Argentine customs (tariff lines 2204.10, 2204.21, 2204.22 and 2204.29, plus alcohol-free wines identified within 2202.99), processed by Vinalitica; January-September 2026 versus January-September 2025. FOB values in current dollars. Data as of 25 October 2026, subject to amendment. The INV published, with provisional data, US$474.4M for January-September 2026 (−4.7%). The two series can differ because of the extraction date, the month to which each shipment is assigned and the treatment of amendments; the gap is concentrated in January-August, and in September both record US$76.8M. The brand is the one declared in each shipment, with spellings merged by Vinalitica's brand register; brands of the same house are not grouped. The winery is the one to which Vinalitica attributes the brand; it may differ from the exporting company and, for retailer own labels, from the owner of the brand. Shipments with no brand (US$34.0M, of which 33.9M bulk) are left out of the ranking; the 45% in the text uses the series total as its denominator, including those shipments, like the 71% of the winery ranking. The US$461.4M with a brand includes 0.6M with no attributed winery. Average FOB price = FOB value / litres. Destinations = distinct declared destination countries, which may differ from the country of consumption. Europe = European Union, United Kingdom, Norway, Switzerland and Iceland. “Since” = first month of the series, which starts in January 2022, with exports declared under that brand. 2025 rank = same calculation for January-September 2025.
See also: Monthly report on Argentine wine exports · Exporting wineries and brands
← Back to the blog